
AI Brings Biggest CFO Shift in 20 Years
Brad Wolfe explains why AI is expanding the CFO role, making data governance, financial oversight, and accountable decision-making more important than ever.
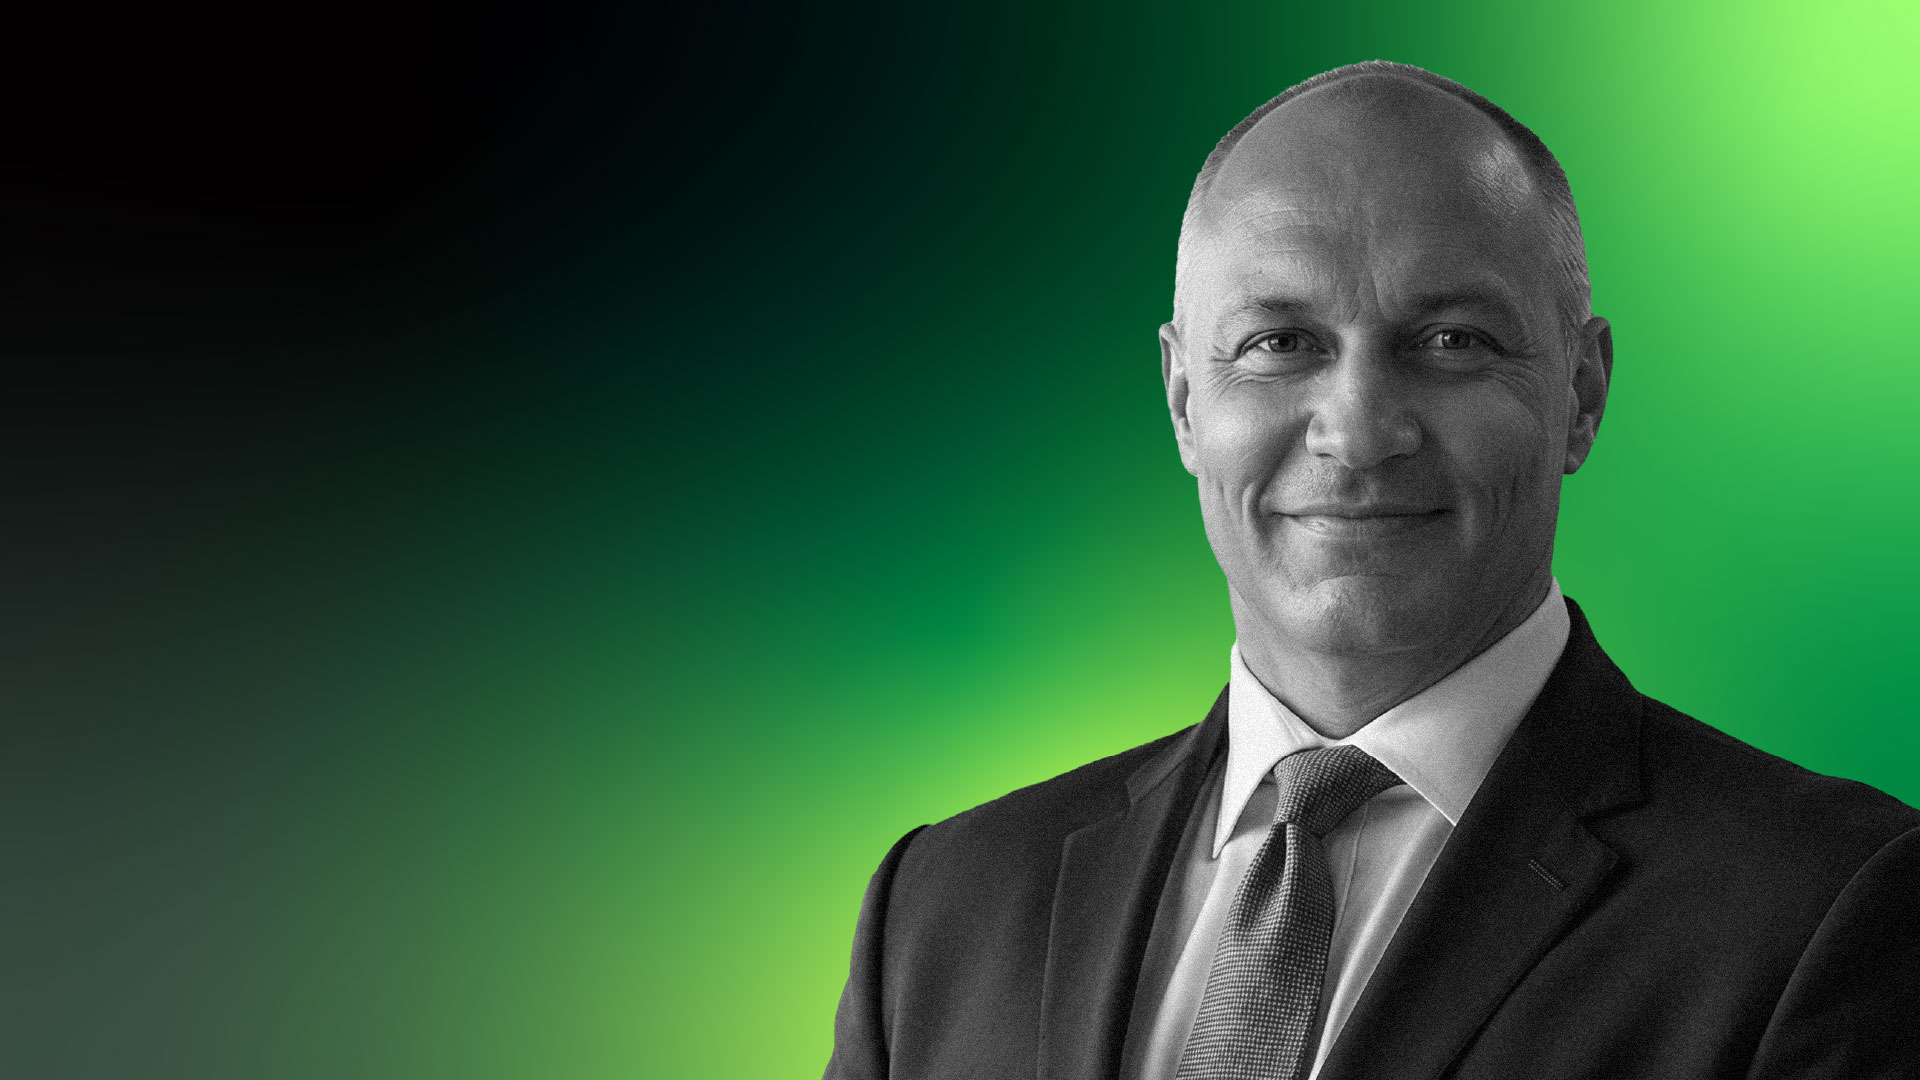
Brad Wolfe
Founder of Wolfe Packs Consulting

AI Impact: AI is shifting CFO roles from traditional tasks to data governance and strategic capital allocation.
Data Governance: AI requires strong data management; ignoring this leads to erroneous financial outputs and decisions.
AI Benefits: Automated AI processes cut monthly close times significantly and improve scenario-based board discussions.
Role Expansion: AI expands the CFO's role, demanding expertise in governance architectures and fiduciary responsibilities.
Ownership Necessity: Failure in AI initiatives often stems from unclear ownership of authority and data management.
In his career, Brad Wolfe has held three NASDAQ CFO seats. Now, he is the founder of Wolfe Packs Consulting, where he supports PE-backed companies in the lower middle market. He also teaches at several universities.
We sat down with him to understand how AI is changing the CFO seat. Here's what he told us.
What This Moment of AI Transformation Requires
I spent the first half of my career doing the work that most CFOs delegate. Three NASDAQ CFO seats, 80-plus M&A transactions, 50-plus enterprise system implementations across ERP, CRM, billing, and data warehousing. PwC background, JD, Kellogg MBA. I have sat in front of audit committees, signed the 302 certifications, and closed deals where the data quality made me uncomfortable enough to reprice.
My reason for being here is simple: I saw AI handed to the wrong people. Not because technology people are incompetent — they are not — but because the questions AI raises are not technology questions. They are capital allocation questions. They are liability questions. These are the questions that already land on the CFO's desk when AI's output is wrong, and someone certifies what was produced.
I run Wolfe Packs Consulting now, working with PE-backed companies in the lower-middle market. My core thesis is that the CFO seat — or what I call the COFO seat when the operating mandate is integrated — is the only executive position that already owns the financial model, the controls, the certification exposure, and the board relationship. AI governance does not need a new title. The existing seat needs to claim the territory upstream of the output.
That is my focus. And that is what this moment requires.
Building What's Needed
I work as an Operating Partner and CFO embedded in PE-backed companies in the lower middle market. The typical engagement is a company between $20 million and $500 million in revenue, backed by a sponsor who has either just closed the deal or is 12 to 18 months into the hold and realizes the finance function isn't built for what comes next.
The complexity varies, but the pattern is consistent: multi-entity structures, often the result of roll-up activity, with finance teams designed for a single-company operating model now asked to produce consolidated reporting, integration accounting, and AI-ready data architecture simultaneously. No shared services infrastructure. Reporting lives in spreadsheets. CFOs are technically capable, but operationally overwhelmed.
My role as COFO is to sit in the seat, build what's needed, and transfer the capability — whether that means standing up the financial model, sequencing the systems work, owning the board relationship during a transition, or defining what AI governance looks like inside a company with real operational complexity and a sponsor who wants answers, not frameworks.
I work with one engagement at a time at that depth. I spend the rest of my time advising, writing, and teaching — Northwestern, DePaul, Chicago Kent — because the gap between what the CFO seat requires today and what finance leaders are trained to do is large enough to require addressing at both the practitioner and pipeline levels.
How AI Enables Integrated Financial Modeling
The most concrete change I've made in the last year is how I build and maintain the integrated operating and financial model.
Before, model building was a periodic exercise. A budget cycle produced a version; a reforecast updated it; and a handful of people understood the model's logic in Excel. By the time a board meeting arrived, the model was already stale, and the narrative had to paper over the gaps.
I now use AI to maintain a continuously updated model that connects operational drivers directly to financial outcomes — revenue by cohort, headcount to labor cost, vendor spend to margin by business unit. I do not rebuild the model quarterly. I maintain it as a living document that can be interrogated in real time.
Because of this, board conversations have changed. Instead of presenting a static snapshot and defending its assumptions, I can walk into a board meeting and run scenarios in the room. A sponsor asks what happens to EBITDA if the largest customer churns — the answer is not "I will get back to you." It is in the model, and it is current.
This change also impacted how I think about AI governance. Once executives make decisions from an AI-assisted model, data quality becomes an existential question. The model does not know what is missing. It executes against whatever is there. This forced a discipline around data governance and process documentation that most lower middle market companies have never had.
AI did not create that requirement. It made ignoring it expensive.
An AI-Powered Variance Analysis Workflow
The AI has already traced the variance to its source — a specific customer, a specific cost center, a specific transaction type — so the review is not a hunting exercise. It is a judgment call: Is this noise, a trend, or a control issue requiring escalation?
Here's how AI-assisted variance analysis, connected to the integrated operating and financial model, runs end-to-end.
A documented Lead-to-Cash process forms the foundation — every revenue-generating step from initial opportunity through cash collection, mapped to its systems. This must exist before adding the AI layer. Without it, the model lacks process logic for validation.
From there, ERP and CRM systems feed actuals into the model daily. AI monitors incoming data against expected patterns — revenue by cohort, collections timing, expense by category against budget — and flags variances exceeding defined thresholds. It flags only those that are statistically significant or deviate from the model's driver assumptions.
I review a flag the same day it surfaces. The AI has already traced the variance to its source — a specific customer, a specific cost center, a specific transaction type — so the review is not a hunting exercise. It is a judgment call: Is this noise, a trend, or a control issue requiring escalation?
That review's output directly feeds the board narrative. When I prepare for a board meeting, I edit the variance analysis; I don't build it. The model has already produced the first draft of the story. My job is to validate the logic, apply judgment requiring operational context, and ensure I can certify the narrative I present.
The governance layer enabling this work includes: named data owners for each source system, a documented escalation path for model exceptions, and a clear distinction between what the AI flags and what the CFO decides. The AI does not make the call. It surfaces information fast enough to make the call before the problem compounds.
Anthropic's Claude Is Vital for Finance Leaders
Claude, Anthropic's large language model, is my go-to tool. Not because it is the only capable model — it is not — but because I have found it most useful for the work that matters in a CFO context: long-form reasoning, synthesizing complex financial and operational information, drafting board-level narratives, and working through governance frameworks requiring sustained logical consistency across a long document.
It delivers the most value in a specific use case: building and maintaining the Master Briefing — a living document tracking every active relationship, content thread, vocabulary decision, and open item across my advisory and content platform. This task does not fit in a single prompt. It requires a model that holds context, reasons about dependencies, and produces output consistent with decisions made earlier in the same session. Here, the quality difference between models is most visible.
Why CFOs Must Defend Decisions Informed by AI
But the more important point is not which tools I love, but what I use them for.
AI informs variance analysis, scenario modeling, forecasting, cash flow pattern recognition, and the first draft of almost any analytical output. These are areas where data volume exceeds what a human analyst can efficiently process, and where value lies in surfacing the signal, not in a human performing the arithmetic.
AI does not decide capital allocation, revenue recognition judgments, board-level risk assessment, or anything that requires certification. These remain explicitly human — not because AI cannot produce an answer, but because the answer carries legal and fiduciary consequences that must terminate with a named human who can defend it under adversarial review.
Most CFOs are currently mismanaging the middle layer — AI-assisted outputs that inform decisions without explicit accountability for the output. Variance analysis that feeds a board narrative. Cash flow projections that drive covenant conversations. These are not low-stakes. The CFO who allows AI to inform those outputs without a governance architecture for data quality, model validation, and output certification is signing a 302 on a number they cannot fully explain. That is not an AI problem. That is a controls problem.
AI Comes with Big Benefits and Big risks
First, the good results.
The close cycle time is most visible. When we correctly sequenced data work before deploying AI-assisted reporting, monthly close time dropped materially — in one case from 18 days to 9. That is not magic; it happens when data is clean enough for automation to work without manual intervention at every step.
Forecast accuracy improved differently than I expected. The improvement was not in number precision, but in revision speed. When actuals diverge from plan, the model identifies the variance and traces it to the driver within hours instead of days. The CFO is not explaining a miss at the board meeting. The CFO is already managing the response.
The most important qualitative result: the board conversation changed. When the model is current and the scenarios are pre-built, the sponsor asks better questions, and the CFO gives better answers. That changes the relationship.
Next, the bad.
AI Success Requires Good Data Infrastructure
The most consistent failure mode I have seen is deploying AI on top of a data problem the organization did not know it had.
Every CFO starting an AI initiative believes their data is in reasonable shape — the ERP has been running for several years, the chart of accounts is standardized, the CRM is populated — but that's almost never the case. Data quality assessments usually reflect how the data looks to the people who entered it, not how it looks to a model trying to use it.
The issues were always there — inconsistent categorization, undocumented processes, revenue recognition policies agreed to in a board meeting but never configured into the billing system, and customer records with three versions of the same name. The finance team learned to work around them. The AI cannot.
So, AI does not flag bad data. It processes it confidently and produces output that looks authoritative. A finance team that trusts the output without understanding the input is in a more dangerous position than a team using spreadsheets — because at least with spreadsheets, someone usually knows where the bodies are buried.
What I have learned is that data governance should be the first deliverable, not the prerequisite everyone agrees to in principle and skips in practice. This means mapping the Lead-to-Cash process before selecting any AI tool — every handoff, every system touchpoint, every place where data changes hands and could be miscoded, misdefined, or lost.
Then assign a named owner to each layer — not a department, but a person — and document what correct looks like at each step. That means named owners for each data domain, documented definitions for every metric the model will use, and a reconciliation between what the policy says and what the system actually does — before selecting the AI tool, not after deploying it.
The cost of getting this wrong is not just data cleanup. It includes retraining, revalidation, loss of confidence in the output, and in some cases, the restatement conversation. That cost was not in the business case. It never is.
AI Fails Unless Owners Are Named
By the time the organization realizes it needs documented data ownership, named approvers, and an escalation path for model exceptions, AI is already embedded in workflows nobody fully understands. Retrofitting governance is significantly harder and more expensive than building it before deployment.
The second failure is governance lag — and an unwillingness to name an owner.
AI adoption in finance most often stalls not because the technology is wrong or the implementation is complicated, but because nobody in the organization has been given — or claimed — the authority to make the decisions that AI deployment requires.
By the time the organization realizes it needs documented data ownership, named approvers, and an escalation path for model exceptions, AI is already embedded in workflows nobody fully understands. Retrofitting governance is significantly harder and more expensive than building it before deployment.
Who defines what the data has to look like before the model touches it? Who approves the exceptions when the model produces an output that does not match the policy? Who is accountable when the AI-assisted analysis informs a decision that turns out to be wrong?
These are not technology questions. They are authority questions. And in most organizations, they get answered the same way every other uncomfortable authority question gets answered: with a committee.
Why AI Falls Short in Vendor Analysis and Strategy
AI has not delivered in vendor contract analysis and procurement intelligence. The promise was that AI would surface savings opportunities buried in contract terms, identify duplicate spend, and flag unfavorable renewal conditions before they rolled. In practice, the data feeding these tools is almost never clean or complete enough for actionable output.
Contracts are in PDFs with inconsistent formatting, vendor records have three versions of the same supplier name, and spend categorization, which was supposed to be standardized, never actually was. AI produces a report that requires manual validation, which takes longer than the original analysis would have.
I see the same pattern everywhere: The tool works in the demo because we prepared the demo data. It underdelivers in production because we did not prepare the production data.
How AI Reshapes Finance Teams and Talent Needs
AI is changing the finance team's shape in ways most org charts haven't yet caught up with.
Traditional finance teams were built around headcount that included a controller, a team of accountants, one or two FP&A analysts, and a CFO managing them all. That structure assumed humans performed repetitive, high-volume tasks: closing the books, reconciling accounts, building variance reports, and maintaining the budget model.
AI automates a significant portion of that work. The question isn't whether headcount changes. Instead, organizations must recognize that the finance workforce now includes four distinct categories, each requiring different management, governance, and cost structures: employees, AI agents, contractors, and consultants.
Most finance organizations use all four without acknowledging the distinction. An AI agent processing invoices is not an employee. It doesn't have a meaningful manager. It has someone who owns the process — someone who defines its parameters, validates its outputs, and is accountable for incorrect processing. Organizations must name that owner. Most organizations haven't named them.
I see the talent mix shifting: high-volume transactional work is moving to agents. The remaining human work requires judgment, context, and accountability — the CFO who certifies the output, the Controller who knows where the bodies are buried in the data, and the analyst who understands why the model produces a number that doesn't match business reality.
The most effective finance teams three years from now will be those that deliberately redesign their workforce architecture now — not those that reduce headcount and hope agents will fill the gap.
How AI Has Created a Mandate Expansion for CFOs
A lot of people think the CFO seat is contracting. AI is automating the close, the reconciliation, the variance analysis, and the first draft of the board narrative. The headcount required to run a finance function is going down. The argument writes itself.
But I think the seat is expanding, and the CFOs who understand that are the ones who will define what the role looks like for the next decade.
Here's why. AI is automating the commodity work. What it cannot automate is the accountability structure that makes the output usable — the governance architecture that determines whether the AI's output is certifiable, the capital allocation judgment that decides which scenario to act on, the board relationship that makes the recommendation credible, and the SOX 302 signature that puts a human name on the consequence when something goes wrong.
All of that is concentrating upward. The trusted advisor tier of finance — the CFO who owns the integrated model, governs the AI output, and carries the fiduciary exposure — is not shrinking. It is becoming more consequential as the volume of AI-generated output that requires human certification grows.
CFOs who will lose ground built their identity around work that is being automated. CFOs who will gain ground claim the mandate upstream of the output — data governance, process architecture, AI governance as a capital function — before someone else fills the vacuum.
This moment is not a threat to the CFO seat. It is the largest mandate expansion the seat has seen in twenty years. Most CFOs have not noticed yet.
Why CFOs Must Shift Their Focus Now
So, my advice? Three things, in order of importance.
- Own the architecture first. The CFO who waits for an AI tool to expose data problems is already behind. Data governance, process documentation, and systems alignment are prerequisites, not byproducts. If you do not know who owns each data domain, what the revenue recognition policy says in the billing system, and how your Lead-to-Cash process works end to end, you are not ready to deploy AI. You are ready to fund the cleanup that follows a failed deployment.
- Claim the mandate upstream of the output. AI governance is landing on the CFO's desk whether the CFO asked for it or not. The certification exposure under SOX 302, the board-level questions about model risk, the capital allocation decisions around AI vendor contracts — these already belong to the CFO by function. The CFO who treats AI as an IT problem voluntarily gives up the territory that defines the next version of the seat. The CFO who owns the integrated operating and financial model, the Lead-to-Cash process, and the governance architecture that makes the output certifiable does not just survive this moment. The board and the sponsor will rely on that CFO as the stakes get higher.
- Do not build your professional identity around work that is being automated. The close, AP, reconciliation, and basic reporting — these are becoming commoditized. The CFO who built their credibility entirely around executing the close will find that credibility hollowing out faster than the job description changes. The work that compounds is the work that cannot be commoditized: capital allocation judgment, board-level trust, governance architecture, and the ability to certify that what the model produced is something you are willing to put your name on.
This moment is not a threat to the CFO seat. It is a mandate expansion. The CFOs who see it that way will define what the seat looks like for the next decade.
So, my advice? Three things, in order of importance: Own the architecture first. Claim the mandate upstream of the output. Do not build your professional identity around work that is being automated…This moment is not a threat to the CFO seat. It is a mandate expansion. The CFOs who see it that way will define what the seat looks like for the next decade.
Follow Along
You can follow Brad Wolfe's work on LinkedIn and check out Wolfe Packs Consulting.
More expert interviews to come on The CFO Club!